
The REPC Is a Leagally Binding DocumentTo start out this post, it is best to understand that when a buyer submits a REPC to a seller, the buyer is committing his or herself to the terms of the
Utah Home Down Payment Options and Payments: Everything First Time Buyers Need to Know
When you start exploring homeownership in Northern Utah, three critical questions typically come to mind:
What down payment amount will I actually need?
Can I really afford a $650,000 property?
What salary level qualifies me for a Utah mortgage?
Whether you are currently renting in Ogden, living with relatives in Layton, or saving up in Clearfield, there is encouraging news. Homeownership in Weber County and Davis County is far more accessible than most people realize, thanks to innovative low down payment financing and state sponsored assistance programs.
This comprehensive post provides actual numbers, detailed program information, and credible resources to help you determine if now is the right time to purchase your first home. Before diving into the numbers, you might want to check out our detailed post on what house you can afford in Utah to understand your complete financial picture.
Understanding Down Payment Requirements in Utah
The loan program you select determines your down payment requirement far more than the property's purchase price. Buyers throughout Ogden, Roy, Layton, Clearfield, Clinton, and neighboring communities typically choose from these financing options.
Popular Mortgage Programs for Northern Utah Buyers
| Program Type | Required Down Payment | Ideal Candidate Profile |
|---|---|---|
| FHA Mortgage | 3.5 percent | Average credit scores with smaller savings accounts |
| Conventional Financing | 3 percent | Higher credit ratings and solid financial profiles |
| VA Mortgage | 0 percent | Military veterans and current service members |
| USDA Financing | 0 percent | Purchases in qualifying rural zones of Weber or Davis County |
The Federal Housing Administration enables borrowers to purchase with just 3.5 percent down when their credit score reaches 580 or higher.
Meanwhile, Fannie Mae backed conventional mortgages give first time purchasers the option of contributing as little as 3 percent for their down payment. For more insights on navigating the mortgage process, read our comprehensive post about Utah mortgage lenders and home loans.
Exploring Utah's Down Payment Assistance Opportunities
Numerous buyers in Weber County and Davis County strategically pair their low down payment mortgages with state assistance, dramatically cutting the cash needed at closing.
Support from Utah Housing Corporation
The Utah Housing Corporation makes available assistance funds equaling up to 6 percent of your total loan value, applicable toward both down payment and closing expenses.
Most recipients receive this support through a secondary mortgage featuring minimal or postponed payment requirements.
Special Program for New Construction Purchases
Utah's innovative first time homebuyer assistance initiative delivers up to $20,000 for qualified individuals buying newly constructed properties.
The $20,000 funding can cover:
- Your required down payment amount
- Transaction closing costs
- Permanent mortgage rate reductions
According to Utah First Credit Union, this program proves particularly valuable in West Haven, Plain City, Syracuse, Clinton, and Layton areas where new home construction remains robust.
Access the complete Utah Housing Corporation program documentation for detailed eligibility criteria and application procedures.
Real Numbers: Buying a $650,000 Property in Utah
Let's examine a higher priced scenario since many prospective buyers wonder: Can I actually afford a $650,000 house with my current finances?
Down Payment Scenarios Breakdown
| Percentage Down | Upfront Cash Needed |
|---|---|
| 3 percent | $19,500 |
| 3.5 percent | $22,750 |
| 5 percent | $32,500 |
| 20 percent | $130,000 |
The reality is that very few first time buyers in Ogden and Davis County contribute the full 20 percent down payment.
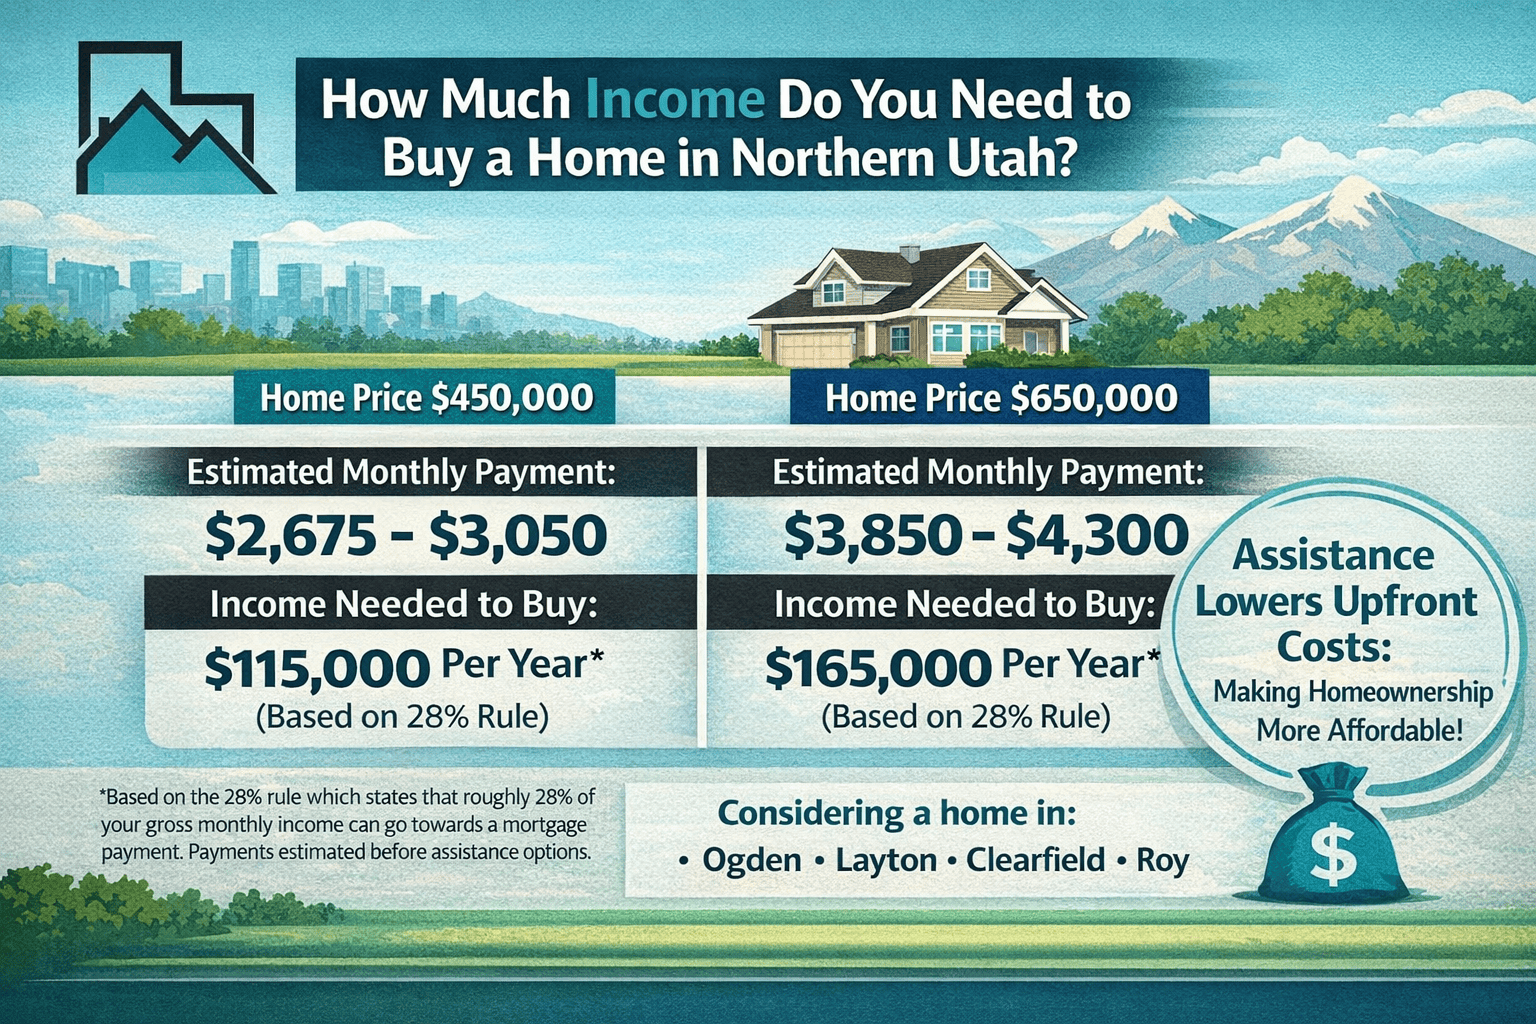
Calculating Your Monthly Housing Costs on a $650,000 Purchase
Key Variables:
- Total purchase price: $650,000
- Down payment: 5 percent
- Financed amount: $617,500
- Loan term: 30 year fixed rate
- Current estimated rate: 6.5 percent
Your Estimated Monthly Obligation
$3,900
Principal and Interest Payment
After incorporating property taxes, homeowners insurance coverage, and required mortgage insurance premiums, most buyers experience total monthly obligations ranging from $4,300 to $4,700, varying by specific location and chosen insurance policies.
Financial experts generally recommend keeping total housing expenses below 28 percent of your gross monthly earnings. Let me connect you with a qualified lender who can provide personalized calculations for your situation.
Scenario Analysis: Purchasing a $450,000 Home with Maximum Assistance
Now let's explore a more typical price point for many Weber County and Davis County buyers, particularly those interested in new construction opportunities.
Required Down Payments for a $450,000 Purchase
| Financing Program | Down Payment Rate | Actual Dollar Amount |
|---|---|---|
| Conventional at 3 percent | 3 percent | $13,500 |
| FHA at 3.5 percent | 3.5 percent | $15,750 |
| VA Program | 0 percent | $0 |
| USDA Program | 0 percent | $0 |
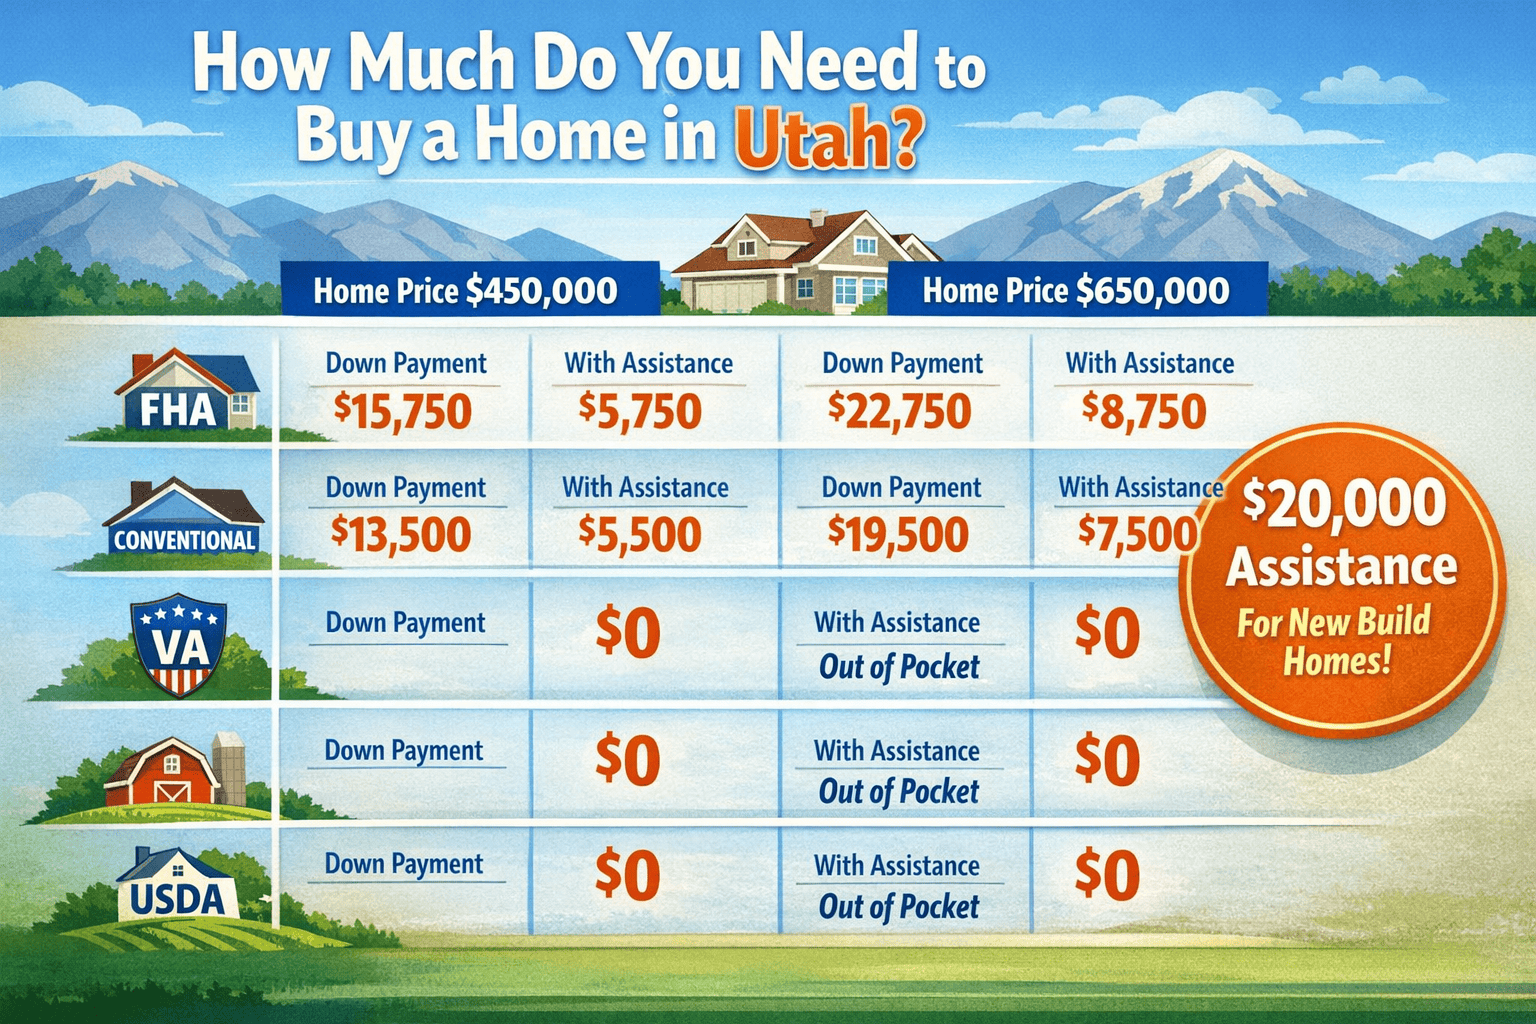
Impact of the $20,000 Assistance on Your Purchase
Qualified buyers purchasing new construction can tap into Utah's generous $20,000 assistance program.
FHA Financing Scenario
- Property price: $450,000
- Standard FHA requirement: $15,750
- State assistance received: $20,000
- Your actual out of pocket: $0
Excess assistance dollars typically apply toward closing expenses or reducing your interest rate for the loan's entire duration.
Conventional Financing Scenario
- Property price: $450,000
- Standard requirement: $13,500
- State assistance received: $20,000
- Your actual out of pocket: $0
Many buyers discover they only need personal funds for home inspections and earnest money deposits, both of which credit back to you at closing.
Projected Monthly Costs on a $450,000 Northern Utah Home
Key Variables:
- Total purchase price: $450,000
- Down payment: covered through assistance
- Approximate loan balance: $434,000
- Loan term: 30 year fixed rate
- Current estimated rate: 6.5 percent
Your Estimated Monthly Obligation
$2,750 to $2,850
Principal and Interest
Including taxes, insurance policies, and mortgage insurance requirements, buyers throughout Ogden, Layton, and Clearfield typically see complete monthly payments between $3,200 and $3,400.
Income Requirements for Utah Home Purchases
Applying the standard 28 percent debt to income guideline:
$450,000 Property
- Projected monthly housing cost: $3,300
- Recommended monthly gross income: approximately $11,800
- Target annual income: approximately $140,000
$650,000 Property
- Projected monthly housing cost: $4,500
- Recommended monthly gross income: approximately $16,000
- Target annual income: approximately $190,000
Recent market data shows Utah property values have climbed considerably over recent years, making careful income assessment increasingly important for prospective buyers.
Remember these represent general guidelines rather than absolute requirements. Buyers carrying minimal debt, maintaining excellent credit, or purchasing with co borrowers frequently qualify with lower income thresholds.
Key Insights for Ogden, Weber County, and Davis County Buyers
Essential Takeaways
- The traditional 20 percent down payment requirement no longer applies to most buyers
- Typical first time purchasers successfully buy with 3 to 3.5 percent down
- New construction buyers can secure up to $20,000 in state assistance
- Properties priced at $450,000 may need minimal or zero personal down payment funds
- Monthly mortgage obligations often mirror current rental rates throughout Northern Utah
Common Questions About Utah Home Down Payments
What is the minimum down payment required to buy a home in Utah?
Utah homebuyers have access to multiple low down payment options. FHA loans require just 3.5% down, conventional mortgages allow 3% down for qualified buyers, and VA or USDA loans offer 0% down payment options for eligible purchasers. Your specific loan type determines your minimum requirement.
What are the monthly payments on a $650,000 home in Utah?
On a $650,000 purchase with 5% down and a 6.5% interest rate, expect principal and interest around $3,900 monthly. When you factor in property taxes, homeowners insurance, and mortgage insurance, total payments generally fall between $4,300 and $4,700 per month.
What income is needed to purchase a house in Utah?
For a $450,000 home with estimated monthly costs of $3,300, lenders typically look for around $140,000 in annual income. A $650,000 property with $4,500 monthly payments would require approximately $190,000 yearly income. Keep in mind that strong credit scores and low debt can help you qualify with lower income levels.
Are there down payment assistance programs available in Utah?
Yes, Utah offers robust assistance options. The Utah Housing Corporation provides funds equal to 6% of your loan amount. Additionally, buyers purchasing new construction priced under $450,000 can access up to $20,000 through the state's First Time Homebuyer Assistance Program to cover down payment, closing costs, or rate buydowns.
Is a 20% down payment mandatory when buying a home?
Absolutely not. The majority of first time buyers in Northern Utah purchase homes with 3 to 3.5% down. Veterans and buyers in rural areas can even qualify for 0% down loans. The 20% requirement is outdated and no longer reflects today's mortgage landscape.
How does Utah's $20,000 homebuyer assistance work?
This program targets first time buyers purchasing newly built homes priced at $450,000 or less. The $20,000 comes as a zero interest loan with no monthly payment requirement. You repay the funds when you eventually sell or refinance the property, making it an excellent way to reduce upfront costs.
Which Northern Utah cities are covered by these programs?
These down payment options and assistance programs serve buyers throughout Ogden, Roy, Layton, Clearfield, Clinton, West Haven, Plain City, Syracuse, and surrounding communities in Weber County and Davis County.
Can assistance programs be combined with different loan types?
Yes, Utah's assistance programs work with FHA, conventional, VA, and USDA loans. For the $20,000 new construction program, you'll need to work with a Utah Housing approved lender and obtain a qualifying mortgage.
Start Your Homeownership Journey Today
For prospective homebuyers throughout Ogden, Weber County, and Davis County, understanding available down payment options and assistance programs represents your crucial first step toward owning property. With financing available from 0% to 3.5% down and potential access to $20,000 in state assistance, purchasing a home in Northern Utah proves more attainable than most people initially believe.
Contact me today to discuss your unique financial situation and explore every available financing option tailored to your needs.
 Wasatch Front Regional MLS - Salt Lake Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties
