
Stepping into homeownership for the first time in Davis or Weber County brings both excitement and major financial choices. Among the biggest decisions you will face: understanding which type of mortgage best fits your situation and budget.
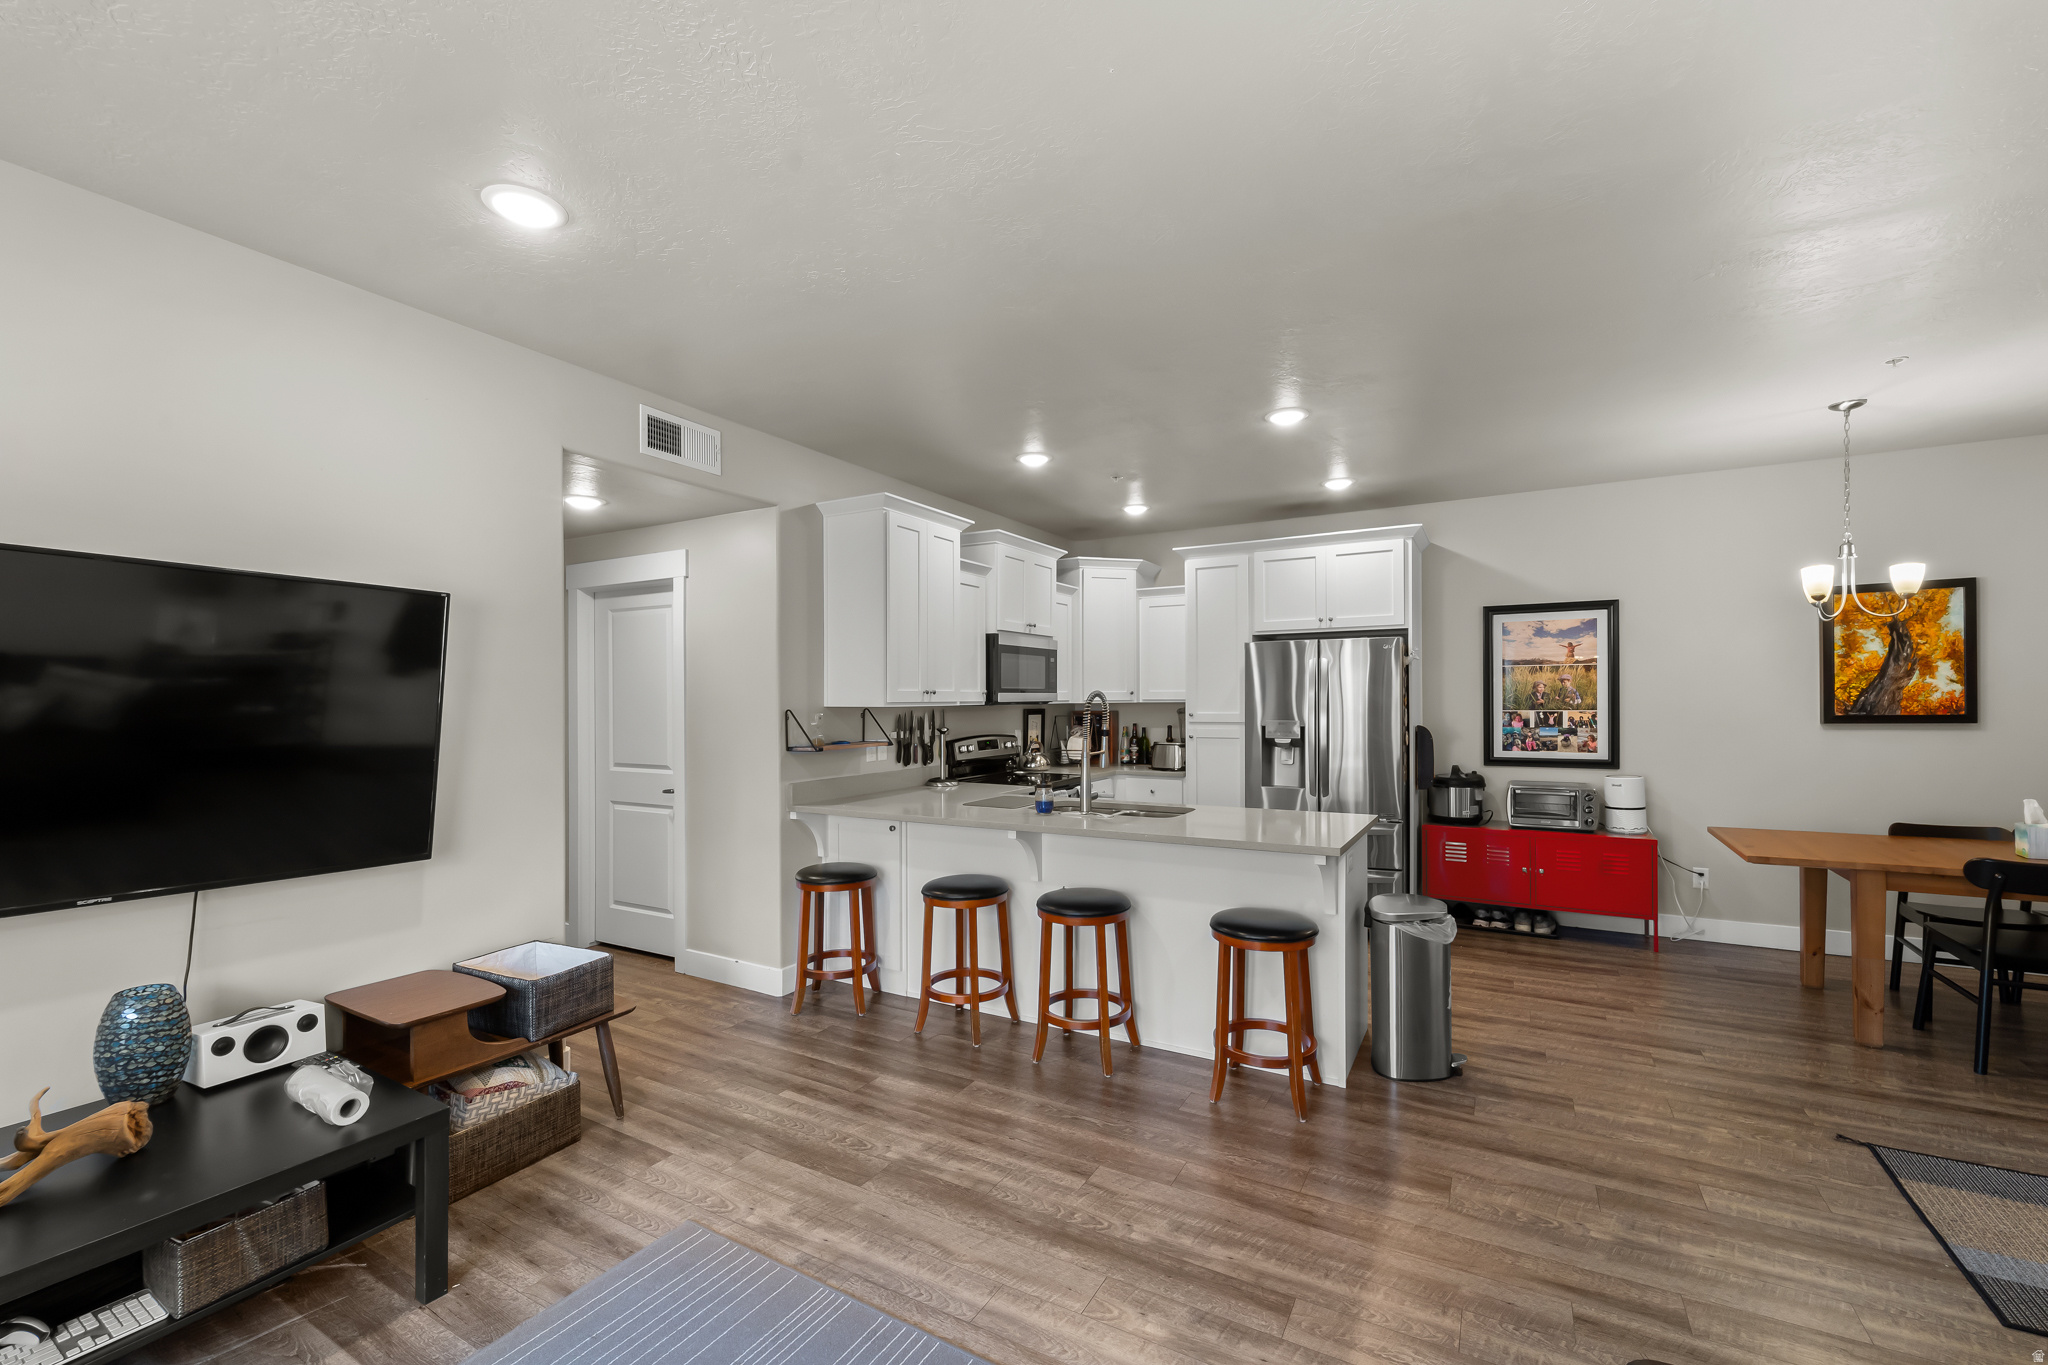 Homes for sale in Utah — Modern properties in Davis and Weber Counties available with FHA or Conventional financing. Photo: Utah MLS
Understanding Your Budget for Utah Real Estate
If you are exploring homes for sale in Utah, particularly in Davis and Weber Counties, pricing varies significantly depending on where you look and what type of property interests you. These two counties remain attractive for buyers seeking value compared to pricier areas across the Wasatch Front.
Current market data shows single family homes still dominate new listings in both counties, representing over 70 percent of available inventory so far this year. Townhomes continue to gain market share and appeal to buyers seeking affordability with lower maintenance responsibilities. Condominiums make up a smaller portion of the market but can provide entry level pricing for budget conscious purchasers.
Several factors determine how much home you can realistically afford:
- Total household earnings
- Existing monthly debt commitments
- Your current credit standing
- Available cash for a down payment
- The financing program you select
The last item on this list is where FHA and Conventional loans create different outcomes for your purchasing power.
Property Type Breakdown Across Davis and Weber Counties
Understanding the local housing mix helps you plan your search strategy. Single family homes remain the dominant option, meaning competition can be intense for properties priced well. Townhomes offer an increasingly popular middle ground with manageable upkeep and moderate pricing. Condos appear less frequently on the market but deliver the most accessible price points, though buyers need to account for HOA dues and specific lending requirements. Remaining open to different property styles expands your opportunities.
New Listing Distribution — Year to Date Data
| Home Type | Market Share | Avg Price per Sq Ft |
|---|---|---|
| Single Family | 70.13% | $258 |
| Townhouse | 18.04% | $245 |
| Condo | 4.06% | $259 |
| Other Types | 7.77% | Varies |
Source: MLS listing data for Davis and Weber Counties, 2026 year to date. Figures represent new inventory only. Independent verification recommended.
Main Financing Pathways for First Time Buyers
While multiple loan programs exist, two options dominate the landscape for first time purchasers in Northern Utah real estate markets. For a deeper dive into understanding Utah mortgage lenders and home loans, see our comprehensive guide.
🏦 FHA Financing
FHA mortgages carry insurance through the Federal Housing Administration and serve buyers who may be working with tighter savings or credit histories that need some flexibility.
🏦 Conventional Financing
Conventional mortgages lack government backing and typically demand stronger applicant profiles, though they frequently result in lower long term costs. These loans operate under standards set by Fannie Mae and Freddie Mac.
Grasping how these two programs differ matters when mapping out your path to homeownership.
FHA Mortgages for Utah Home Buyers
Why FHA Financing Appeals to Many
FHA loans attract first time purchasers because the qualification guidelines provide more breathing room. Notable advantages include:
- Acceptance of lower credit scores
- Down payments starting at just 3.5 percent
- Greater tolerance for debt to income ratios
For buyers wondering how much income is truly necessary, FHA programs often make approval possible with earnings that might fall short under other loan types.
FHA Financing Trade Offs
Despite the accessibility, FHA mortgages carry distinct limitations worth understanding. Potential concerns include:
- Mortgage insurance premiums that typically last the entire loan term
- Loan amount caps that may eliminate some neighborhoods from consideration
- More rigorous property inspection standards
In fast moving markets across Davis County and Weber County, these stricter property requirements can occasionally put FHA buyers at a competitive disadvantage when sellers receive multiple offers.
Conventional Mortgages for Northern Utah Buyers
Conventional Loan Strengths
Conventional financing frequently suits purchasers who bring reliable income and solid credit to the table. Key benefits include:
- Private mortgage insurance that disappears once you build adequate equity
- Less stringent property condition demands
- Typically lower total costs when viewed across many years
Many buyers are pleasantly surprised to discover that certain conventional programs permit down payments as modest as 3 percent for qualified applicants.
Conventional Financing Limitations
Conventional loans prove less accommodating in specific situations. Common challenges include:
- Expectations for stronger credit profiles
- Stricter debt to income thresholds
- Reduced flexibility around recent credit problems
For individuals early in their professional journey or managing student loan obligations, FHA financing may feel more realistic.
Comparing FHA and Conventional Options in Northern Utah
No single answer works for everyone. Your optimal choice hinges on your financial picture and homeownership timeline.
| Comparison Point | FHA Program Gov't Insured | Conventional Program Traditional |
|---|---|---|
| Minimum Down Payment | 3.5% | 3% (select programs) |
| Credit Requirements | More lenient, scores in the 500s may qualify | Typically requires mid 600s or higher |
| Mortgage Insurance | Generally permanent for the loan duration | Removable after reaching 20% equity |
| Property Standards | More demanding inspection requirements | Fewer condition restrictions |
| Total Long Term Expense | Higher due to ongoing insurance costs | Lower after PMI removal |
| Ideal Candidate | Limited savings, lower credit, need flexibility | Strong credit, stable income, long term ownership plans |
FHA financing makes the most sense when your credit score sits below the mid 600s, you are working with a smaller down payment fund, your monthly obligations are elevated relative to your income, or you need more forgiving qualification standards.
Conventional financing becomes the smarter path when you bring solid credit, predictable and sufficient income, desire to minimize long term payment amounts, or plan to remain in the property for an extended period.
These distinctions directly influence how much you can spend on Utah real estate today.
Income Requirements for Purchasing in Davis or Weber County
Qualifying income levels vary based on your target purchase price, prevailing interest rates, selected loan type, and current debt load. Resources like the Consumer Financial Protection Bureau provide helpful calculators for estimating affordability.
Recent data indicates that both average and median listing prices per square foot have declined year over year in these counties, potentially improving accessibility for buyers entering the market right now.
As a rough illustration, FHA programs may enable qualification at somewhat lower earnings levels, though monthly obligations could run higher because of mandatory insurance. Conventional programs often require more income upfront but deliver reduced monthly costs over time.
The most reliable method for determining your actual qualification amount involves reviewing specific scenarios with a Utah lender experienced in Davis and Weber County markets.
Moving Forward with Confidence as a Utah Home Buyer
Both FHA and Conventional mortgages serve crucial roles in helping first time buyers access homeownership throughout Northern Utah.
By clearly understanding your financing options, realistic budget parameters, and income requirements, you can approach your search with knowledge rather than uncertainty. Explore homes for sale in Utah with clarity about which loan structure aligns with your financial situation.
Partnering with an experienced Utah Realtor who understands Northern Utah real estate and can connect you with knowledgeable lenders ensures your financing strategy matches both your current means and future goals. Need a Utah Mortgage Calculator?
Common Questions About Utah Home Financing
Ready to Explore Homes for Sale in Utah?
Utah Realtor Jeremy Chamberlain specializes in Davis and Weber County real estate and works with trusted lenders who understand both FHA and Conventional financing for Northern Utah buyers.
Connect with Jeremy ChamberlainExpert guidance for first time buyers. See our Google reviews
 Wasatch Front Regional MLS - Salt Lake Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties
